Why Intercompany Reconciliation Delays the Financial Close—and How Growing Businesses Can Fix It
As organizations grow, they often add new legal entities, locations, shared-service teams and international operations.
That growth creates more transactions between companies within the same group.
One entity may supply products to another. A shared-service company may charge management or technology costs. One company may pay an expense on behalf of another. Businesses may also transfer inventory, provide services or allocate costs across multiple entities.
Each transaction may be valid from the perspective of an individual company.
But when the group begins its financial close, the balances must agree.
That is where the challenge often begins.
Why do intercompany balances fail to match?
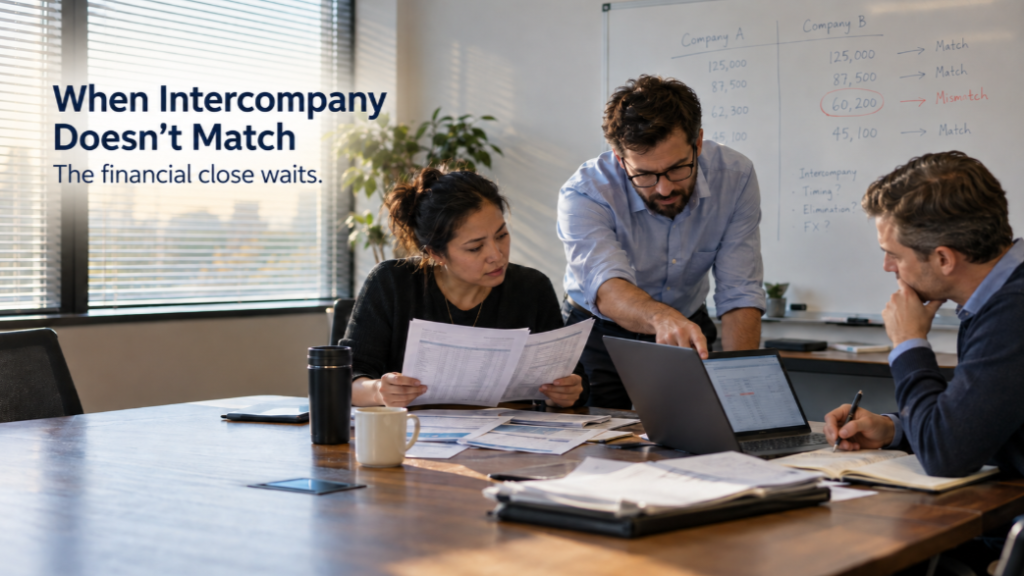
An intercompany difference is rarely caused by one major problem. It is usually the result of several smaller process gaps.
Common causes include:
- One entity posts the transaction before the other
- Different currencies or exchange rates are used
- An invoice is recorded in one period and received in another
- The partner company is entered incorrectly
- Different accounts are used by the two entities
- One company records a gross amount while another records a net amount
- Tax, freight or additional charges are treated differently
- Supporting documents are missing
- A transaction is corrected by one company but not the other
These differences may appear small individually. Across several companies and hundreds of transactions, they can create a significant reconciliation workload.
The problem often appears too late
In many organizations, intercompany reconciliation begins near the end of the reporting period.
Finance teams export balances into spreadsheets, compare receivables and payables, identify differences and contact colleagues in other entities.
The process may involve several rounds of emails:
- Which invoice is missing?
- Who posted this transaction?
- Which exchange rate was used?
- Should the difference be corrected this month?
- Which company owns the next action?
By the time the issue reaches the correct person, the financial-close deadline may already be approaching.
The close team is then forced to choose between delaying reporting, posting a temporary adjustment or carrying the difference into the next period.
Reconciliation is not only a finance-system problem
Technology can help identify differences, but it cannot correct unclear responsibilities by itself.
A reliable intercompany process requires agreement on:
- Which entity creates the original transaction
- Which entity confirms or records the corresponding entry
- Which accounts and partner-company fields must be used
- Which currency and exchange-rate rules apply
- When transactions must be recorded
- What supporting documents are required
- Who investigates each type of exception
- How unresolved differences are escalated
Without these rules, automation may identify more mismatches without making them easier to resolve.
Move reconciliation earlier in the process
The objective should not be to discover every difference during the last days of the financial close.
Organizations should identify and resolve mismatches throughout the accounting period.
A more proactive process can include:
- Regular matching runs before period-end
- Clear tolerance levels for acceptable differences
- Defined ownership for each exception category
- Shared visibility between the affected entities
- Earlier escalation of unresolved items
- Monitoring of recurring root causes
This changes intercompany reconciliation from a month-end investigation into an ongoing exception-management process.
Focus on the source of recurring differences
Correcting a mismatch solves the immediate issue. Understanding why it occurred helps prevent it from happening again.
For example:
- Repeated timing differences may indicate that cut-off rules are unclear.
- Frequent account differences may point to inconsistent mapping.
- Currency differences may indicate that entities follow different exchange-rate procedures.
- Missing partner-company information may require stronger posting controls.
- Repeated invoice disputes may indicate a weakness in the underlying intercompany agreement.
Finance teams should therefore track both the value of unresolved differences and the reasons behind them.
This makes it possible to improve the process rather than repeating the same reconciliation work every month.
How SAP S/4HANA Cloud Public Edition can support the process
A connected Public Cloud ERP environment can provide a more consistent financial-data foundation across entities.
Capabilities such as Intercompany Matching and Reconciliation can help organizations:
- Compare intercompany transactions
- Identify matched and unmatched items
- Review differences at a detailed level
- Assign responsibility for exceptions
- Monitor reconciliation status
- Support earlier resolution before consolidation
SAP describes Intercompany Matching and Reconciliation as a built-in SAP S/4HANA Cloud capability that can match transactions without a separate extract, transform and load process.
The technology is most effective when it is supported by standardized master data, consistent posting rules and clear exception ownership.
What should businesses review before implementation?
Before configuring an intercompany solution, organizations should answer several business questions:
- Which types of intercompany transactions occur?
- Which entities transact with each other?
- What transaction volume is expected?
- Which differences are currently most common?
- Which systems supply the data?
- How frequently should matching be performed?
- What tolerance levels are acceptable?
- Who should resolve each exception?
- How should corrections be approved and posted?
- Which information must be available for audit purposes?
These questions help define a practical implementation scope and prevent the project from becoming only a technical matching exercise.
The real objective is a faster and more controlled close
Successful intercompany reconciliation is not simply about making two balances equal.
It is about creating a process in which differences are identified early, assigned clearly and resolved consistently.
For growing and multi-entity businesses, that can mean:
- Fewer last-minute adjustments
- Better visibility across entities
- Reduced spreadsheet dependency
- Clearer accountability
- Stronger audit support
- A more predictable financial close
Through SAP GROW FAST, RS Integrators helps organizations adopt SAP S/4HANA Cloud Public Edition using standardized processes and a fit-to-standard implementation approach.
The goal is not only to introduce new technology. It is to build connected finance processes that can continue supporting the organization as it grows.
How much of your month-end close is currently spent identifying and resolving intercompany differences?